+
CLOSE
Apply Online


+
CLOSE
Register
+
CLOSE
Quick Enquiry
100% Funded Joint Venture Development in Reading
Deal Structure
- £1.45 million facility
- Facility covered 100% of project costs, including acquisition
- 68% Loan to Gross Development Value (LTGDV)
- 100% Loan to Cost (LTC)
- Interest rate: 12% per annum (rolled up)
- 1% arrangement fee
- 50% net profit share
- 18-month term
Deal Summary
Our client was an experienced property developer with a strong track record of acquiring, developing and selling residential sites.
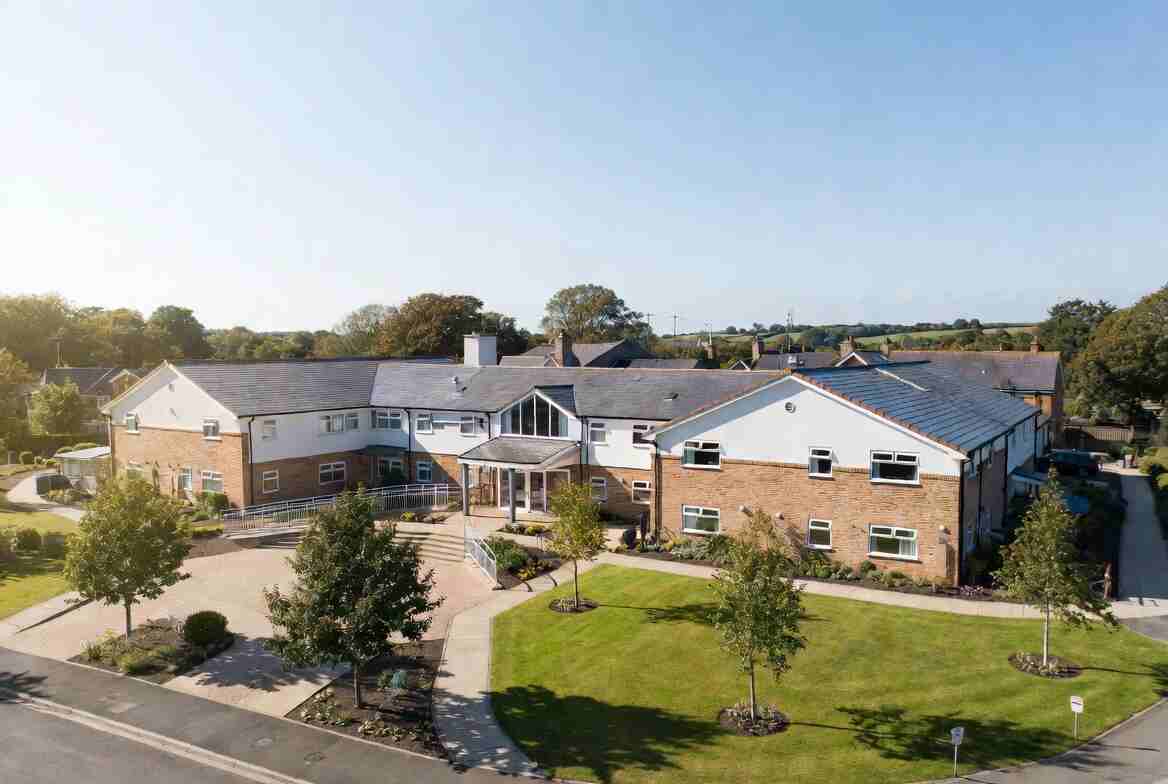
The latest opportunity involved a new-build development of three detached houses near Reading. The client had already agreed to purchase land with detailed planning permission for the three homes.
However, another development opportunity became available before the Reading scheme launched. The client therefore wanted to preserve his own cash resources for the second project.
We explored the option of joint venture development finance. Given the client’s previous experience with similar developments, the project was well suited to our specialist JV funding partners.
Following a successful site visit and full due diligence, we introduced the client to a suitable JV funder.
The funder agreed to provide 100% of the project costs, including the land acquisition, SDLT and Community Infrastructure Levy (CIL). The site was then purchased through a Special Purpose Vehicle (SPV).
The developer initially covered the cost of the required professional reports. However, the JV funder reimbursed these costs when the transaction completed.
The £1.45 million facility provided 100% Loan to Cost and 68% Loan to Gross Development Value, giving the developer the funding required to progress the scheme without committing his own development capital.
The developer remains responsible for the planning requirements and will manage the project from start to finish. He will liaise with the relevant professionals and ensure the development follows the approved planning consent.
This is a self-procured development, so the developer will act as project manager and oversee the construction at cost. He will also manage the sales process once the properties are complete.
The development is expected to qualify for Help to Buy, subject to the relevant eligibility requirements. The developer will manage the associated sales process and liaise with the relevant parties.
The Outcome
The 100% funded joint venture development finance allowed our client to purchase the Reading site and fund the full development without using his own capital for the project costs.
This meant he could preserve his cash resources and pursue another development opportunity at the same time.
The £1.45 million facility provides the funding needed to acquire the site and deliver the three new-build homes, while the agreed 50% net profit share aligns the interests of the developer and JV funder.
If you are an experienced developer looking for 100% development finance or joint venture property funding, Positive Commercial Finance can help identify specialist JV partners and structure funding around your project requirements.
Contact
John Waddicker On 07974703375 or message here

Related case studies

Quick Enquiry