+
CLOSE
Apply Online


+
CLOSE
Register
+
CLOSE
Quick Enquiry
£2.2m Care Home Development Finance in North Manchester for a 12-Bed Conversion
At a glance
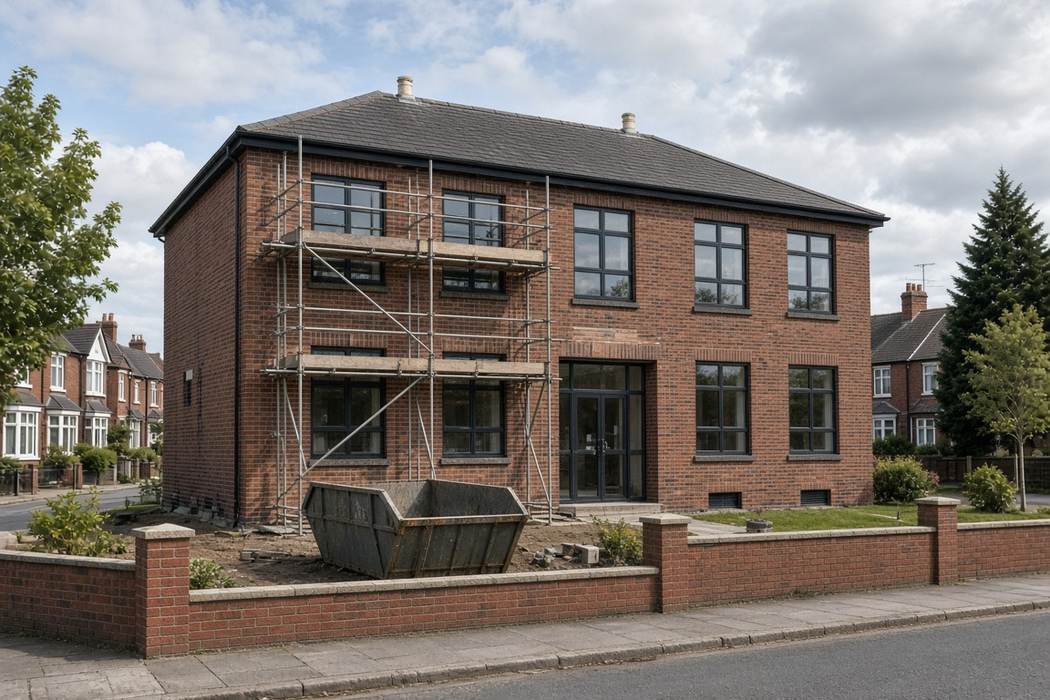
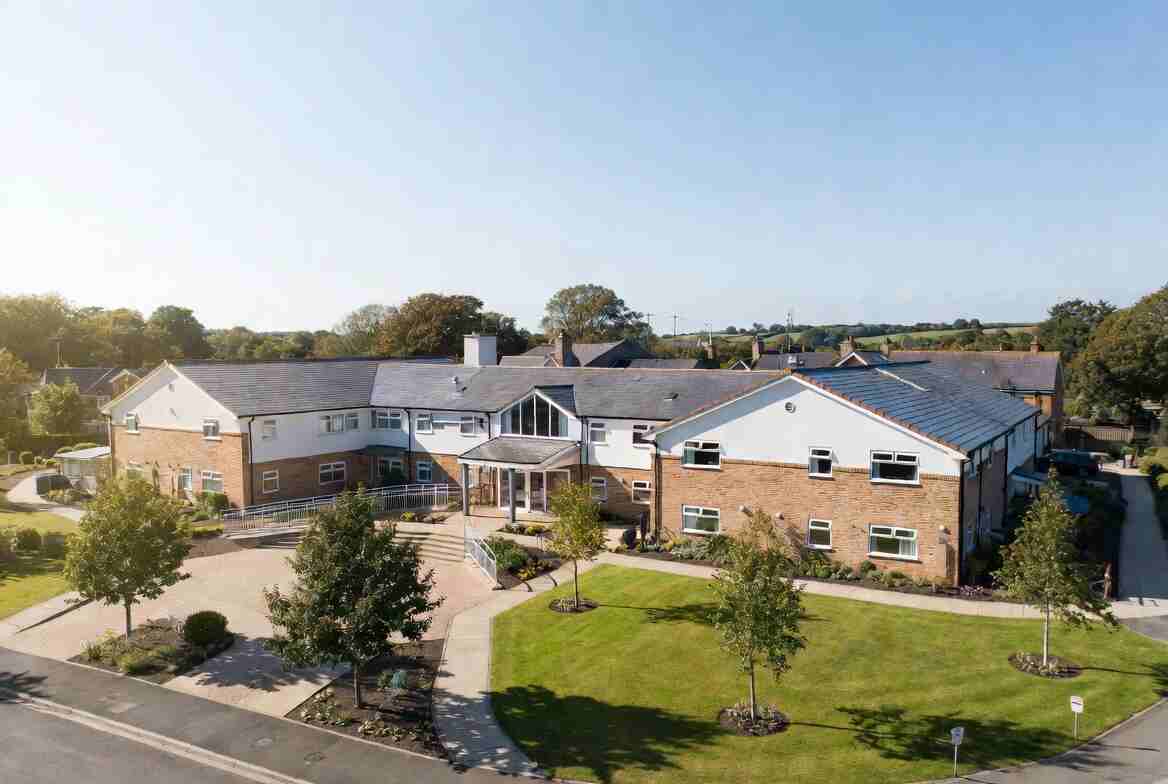
Positive Commercial Finance arranged care home development finance in North Manchester for an experienced specialist care operator. The client owned an empty commercial building outright. They wanted to convert it into a modern 12-bed care home for adults with learning difficulties and mental health needs.
The facility released capital from the owned building and funded 100% of the works, including contingency. Importantly, the proposed use did not require planning permission, which simplified the process and reduced risk. Completion then followed on 5 August 2026.
Deal summary
- Facility: £2,199,750
- Location: North Manchester
- Scheme: Conversion of an empty commercial building into a 12-bed care home
- Original purchase price: Approximately £1.1 million
- Day-one advance: £470,000, to refinance part of the original purchase price
- Build funding: 100% of build costs and contingency, drawn in stages
- Interest rate: 10% per annum fixed
- Term: 24 months
- Arrangement fee: 2%
- Exit fee: None
- Security: First legal charge, a debenture and a capped personal guarantee
- Turnkey valuation: £3.76 million
- Trading valuation: £5.48 million
- Loan-to-GDV: Conservative relative to the £3.76 million turnkey valuation
- Completion: 5 August 2026
The opportunity
Our client was an experienced operator, already active in the specialist care sector. They owned an empty commercial building in North Manchester outright, having purchased it for approximately £1.1 million.
The opportunity was to refinance part of that original purchase price and release capital tied up in the asset. At the same time, the client needed to fund the full conversion into a modern 12-bed care home. This is a typical use of property development loans where a borrower already owns the building and needs the works fully funded.
The proposed use did not require planning permission. As a result, the process was simpler and the risk was lower. The finished scheme had a turnkey value of £3.76 million, rising to £5.48 million on a fully trading basis. That gave the lender strong headroom.
The challenge
However, the borrower needed a facility that would do several things at once. First, it had to release equity from the owned building, in order to improve cash flow. It also needed to cover 100% of build costs plus contingency.
In addition, the loan had to suit a specialist care home conversion, rather than a standard residential or commercial scheme. The borrower also needed a realistic timetable, despite the usual conditions precedent. Those conditions included opening balance sheets, insurance, company structure checks, security documents, and building contracts and warranties.
Several lenders showed early interest, while others declined. Some also requested site visits. Therefore, the case needed careful packaging and lender selection in order to achieve competitive terms.
How we arranged care home development finance in North Manchester
We approached the market from late January and secured heads of terms in late May. After further negotiation, the rate improved, and the lender issued the facility letter in June. The facility then completed on 5 August 2026, once the parties satisfied the final conditions.
The agreed facility was £2,199,750. A day-one advance of £470,000 refinanced part of the purchase price. The balance funded 100% of build costs and contingency, and the borrower could draw it in stages.
The interest rate was 10% per annum fixed, with a 24-month term and a 2% arrangement fee. There was no exit fee. Security comprised a first legal charge, a debenture and a capped personal guarantee. Loan-to-GDV was conservative relative to the £3.76 million turnkey valuation. In addition, the higher trading valuation provided further support.
A monitoring surveyor oversaw drawdowns against certified works. This kept the lender comfortable, while also giving the borrower clear, milestone-based funding.
The result
The facility completed successfully on 5 August 2026. It released capital for the borrower and provided full funding for the conversion. Because the project did not need planning consent, it could move quickly from acquisition refinancing into the works phase.
The structure supports the creation of a purpose-built environment for adults with learning difficulties and mental health needs. In England, the Care Quality Commission regulates care homes of this type. The project also aligns with ongoing demand for specialist care provision in Greater Manchester.
Why this care home development finance in North Manchester matters
This case shows how specialist development finance can unlock equity in an owned asset. It can also fund 100% of conversion costs and deliver a clear exit path on a fixed-rate basis. That remains true even where the asset is a care home, rather than a standard residential scheme.
You can read more about our property development loans, or compare development lenders on our site.
Frequently asked questions
What were the key terms of this development facility?
The facility was £2,199,750, at 10% per annum fixed, over a 24-month term. The arrangement fee was 2%, and there was no exit fee. A day-one advance of £470,000 refinanced part of the purchase price. The balance then funded 100% of build costs and contingency in stages.
Did the conversion need planning permission?
No. The proposed use did not require planning permission. That simplified the process, reduced risk, and helped the project move quickly from acquisition refinancing into the works phase.
How did the facility release cash for the borrower?
The client already owned the empty commercial building outright, having purchased it for approximately £1.1 million. The day-one advance of £470,000 refinanced part of that original purchase price and released capital tied up in the asset.
What valuations supported the loan?
The finished scheme had a turnkey value of £3.76 million, rising to £5.48 million on a fully trading basis. Loan-to-GDV was conservative relative to the turnkey figure. In addition, the higher trading valuation provided further headroom for the lender.
Looking for development finance for a care home, a conversion or a specialist property scheme? We arrange facilities from specialist lenders across the UK with no upfront broker fees. Contact us for a no-obligation discussion about your project.

Contact
James Waddicker On 07977 460546 or message here
Related case studies

Quick Enquiry